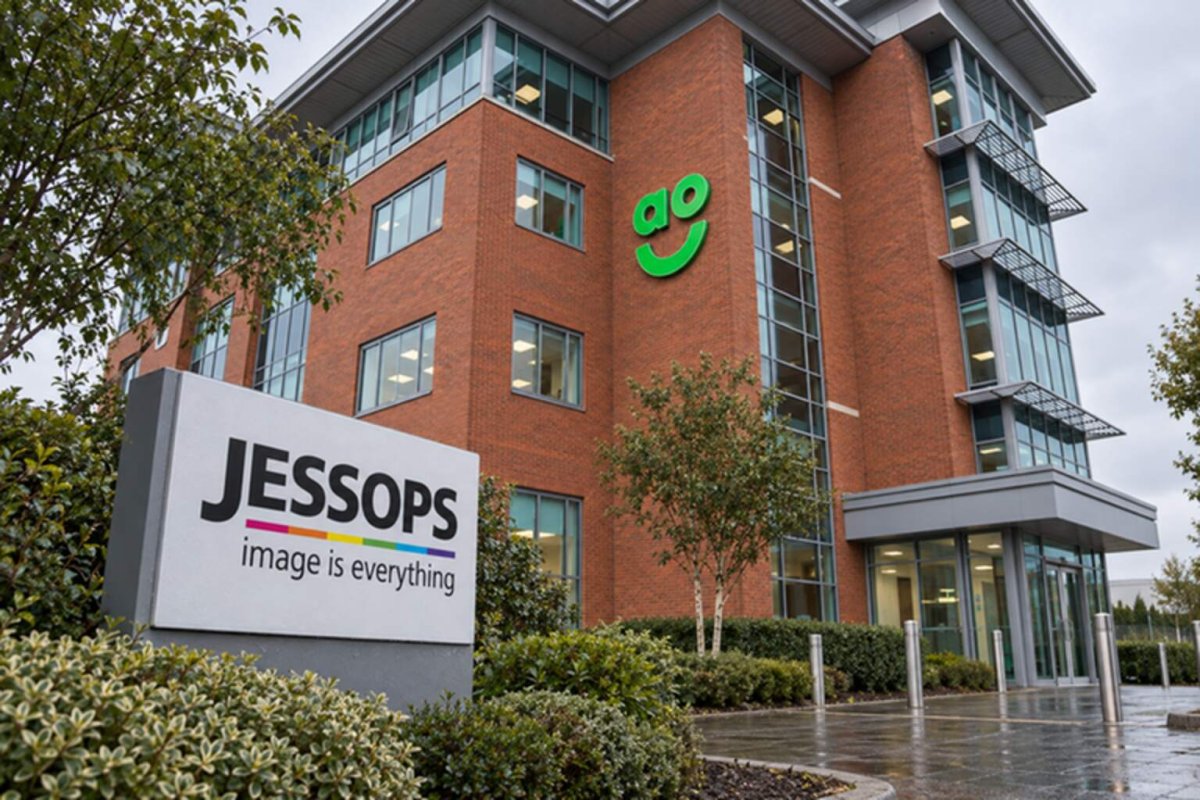
Shares of AO World plc (LON:AO) dropped 4.0% in London trading on Thursday, closing at 89.3 pence, as investors reacted to the company's acquisition of camera retailer Jessops without any accompanying upgrade to its full-year profit forecast. The stock traded as low as 85.0 pence intraday, marking a decline of more than 8% from Wednesday's close of 93.0 pence, before recovering somewhat. Volume surged to 2.87 million shares, more than four times the trailing 20-session average, indicating heightened investor interest and concern.
The electricals retailer announced that it had acquired Jessops for an undisclosed sum, funded entirely from existing cash reserves. While the acquisition expands AO's footprint in the photography market, the company's trading update maintained its previous full-year guidance, a key factor behind the market's negative reaction. According to the update, first-half pretax profit is expected to exceed £21.5 million, but management cautioned that second-half comparisons and ongoing investment costs would continue to cap overall profitability.
Jessops, which operates both physical stores and an online presence, reported revenue of £19.8 million for its fiscal year ended September 28, 2025, along with a pretax loss of £1.0 million. That loss narrowed from £1.17 million in the prior year, while revenue grew 6.5%. In contrast, AO World generated £1.27 billion in revenue for its fiscal year ended March 31, 2026, an 11.4% increase year-over-year, with pretax profit of £50.5 million. The acquisition adds approximately 1.56% to AO's top line, a relatively modest contribution that analysts say does not materially alter the company's financial trajectory.
Chief Executive John Roberts expressed enthusiasm about the deal, stating, "I am delighted to welcome Jessops into the AO family." However, investors appeared more focused on the strategic fit and the potential for synergies. Jessops' Camera Jungle operation, which specializes in used camera equipment, could potentially integrate with AO's musicMagpie subsidiary, a leading reseller of refurbished electronics. The durable question, analysts say, is whether the two businesses can share a common processing network for pricing, refurbishment, and resale, creating operational efficiencies that would justify the acquisition.
The company's balance sheet remains solid, with free cash flow of £66.4 million in fiscal 2026 and a net fund position of £16.4 million, a turnaround from prior net debt. This financial strength enabled the cash-funded acquisition without straining liquidity. AO also noted that headroom remains above £200 million, providing flexibility for future investments, including its ongoing ERP system upgrade.
Despite Thursday's decline, analysts remain bullish on AO World. Jefferies maintains a Buy rating with a target price of 160 pence, implying 79.2% upside from the current level. Peel Hunt also rates the stock a Buy with a target of 137 pence, representing 53.4% upside. The consensus target among two analysts is 148.5 pence, suggesting 66.3% upside. However, these recommendations predate the trading update and may be revised in light of the acquisition's details, which were not fully disclosed.
The market's reaction underscores a broader concern: AO World's first-half revenue grew 5.5%, and pretax profit rose more than 20%, but the company's failure to raise full-year guidance suggests that management sees limited upside in the near term. The integration of Jessops, along with the costs associated with the ERP implementation and tougher year-over-year comparisons in the second half, are likely to weigh on margins. AO has set a long-term goal of achieving a 5% pretax margin, but this target may be delayed.
Investors will get more clarity when AO World publishes its half-year results on November 24. At that time, management is expected to provide details on the acquisition's cash cost, integration progress, and any potential synergies. Until then, the market appears cautious, with the stock trading at a discount to analyst targets.
In the broader context, the acquisition of Jessops represents a strategic move to diversify AO's product offerings and strengthen its position in the circular economy, a growing segment as consumers increasingly seek refurbished goods. However, the near-term financial impact is modest, and the lack of an earnings upgrade suggests that the company is prioritizing long-term investments over immediate shareholder returns.