Archer Aviation Inc. (NYSE: ACHR) saw its shares decline 2.6% on Friday, closing at $5.26, as the expiration of legacy warrants removed one potential equity claim, but investors now focus on a larger dilution event tied to Boeing's pending investment.
Trading volume reached 46.7 million shares, nearly double the 20-day average, signaling heightened activity. The stock's decline came two days after the expiration of warrants with an $11.50 exercise price, which had become worthless as the share price remained well below the strike.
The expiration eliminates one source of future share issuance, but Archer's dilution debate is far from over. A pending transaction with Boeing could result in the issuance of approximately 152 million new shares, based on the company's current share count of 770 million. This would represent a 19.75% stake in Archer, or about 16.5% of the enlarged total.
Boeing's involvement extends beyond equity. The aerospace giant is set to acquire Wisk Aero, SkyGrid, and Insitu, with Insitu alone expected to contribute over $200 million in annual revenue. Boeing would also become a strategic partner, providing technology and manufacturing support.
However, Archer's financial position remains a concern. The company reported just $5 million in second-quarter revenue, while operating expenses ballooned to $284 million, and net losses widened to $263 million. Cash and short-term investments fell by $215 million during the quarter, leaving $1.56 billion in liquidity, which at the current burn rate covers roughly seven quarters.
Archer's cash consumption is significant: operating cash use was $156 million in Q2, plus $37 million in capital expenditures and $25 million for its Hawthorne Airport operations. The company's adjusted EBITDA loss widened to $177 million.
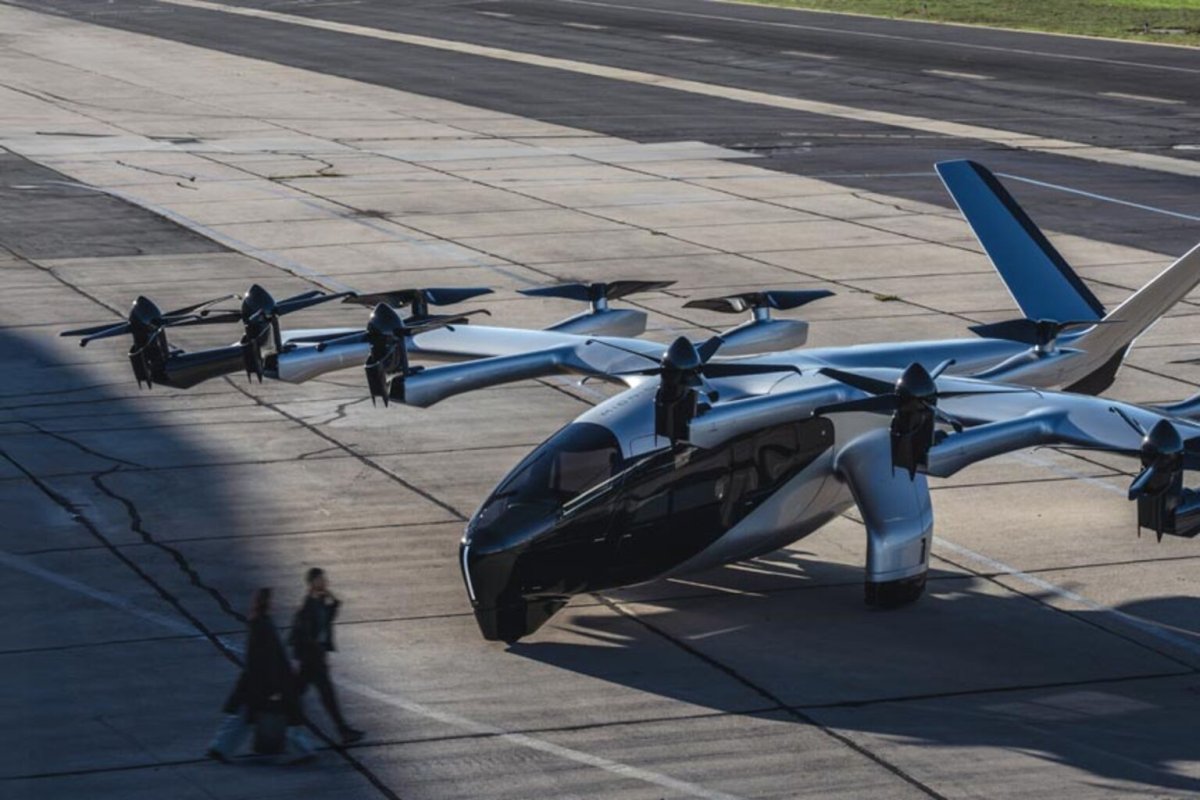
Despite these challenges, Archer has made progress in its flight testing program. The Midnight aircraft completed over 70 test flights in August, including a 40-mile round trip between Salinas and Hollister, with each leg taking about 12 minutes.
Analysts remain optimistic, with price targets ranging from $8 to $12, well above Friday's close. Cantor Fitzgerald, Canaccord Genuity, and Raymond James all reiterated Buy ratings in August, while Goldman Sachs maintains a Hold. The consensus assumes Archer will successfully navigate certification and commercial launch.
Investors will get a clearer picture when Archer reports third-quarter earnings on November 5. The key metrics will be cash burn and revenue growth, as well as any updates on the Boeing deal's closing conditions.