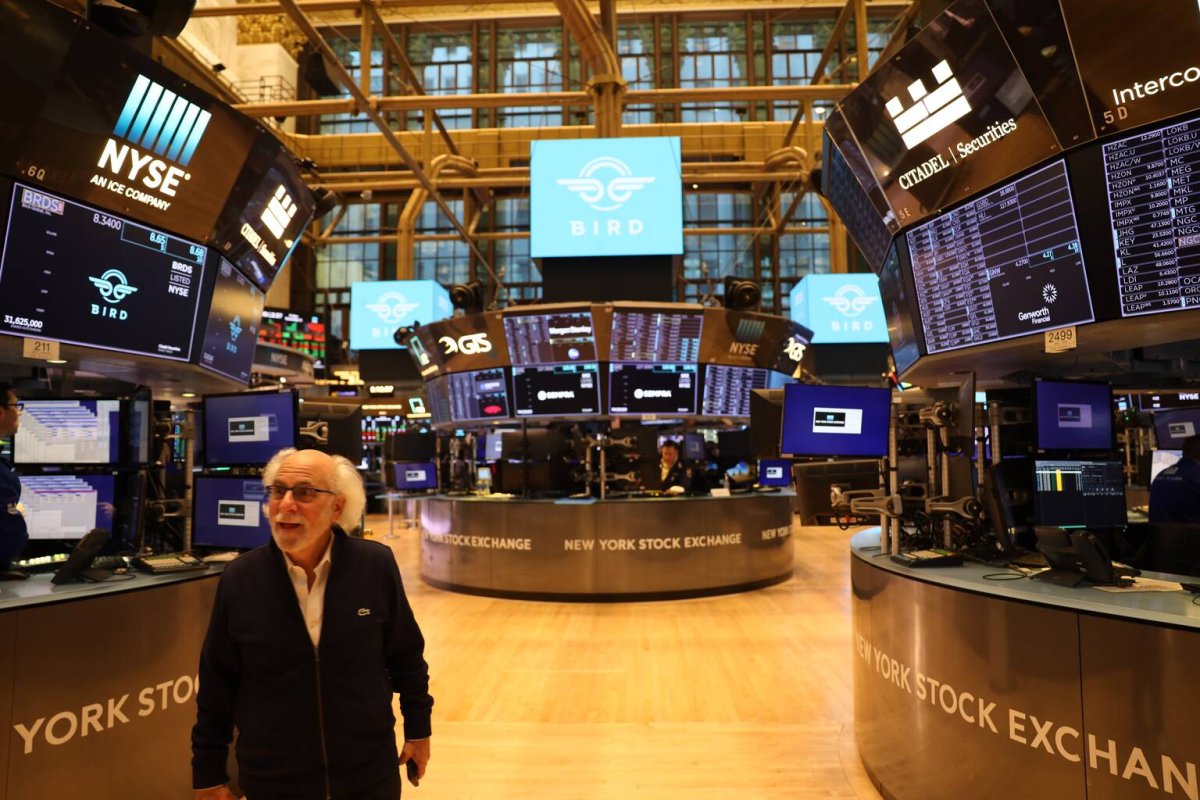
U.S. equities extended their midday gains on Monday, propelled by a wave of takeover activity that lifted software shares and broadened the market's advance. By 12:55 p.m. EDT, the Nasdaq Composite had climbed 0.86%, while the S&P 500 rose 0.63%, bringing it within 0.6% of its all-time high. The Dow Jones Industrial Average added 0.17%, and the small-cap Russell 2000 gained 0.66%.
The rally's breadth improved notably after the opening bell. Shortly after the market opened, only two of the 11 major sector exchange-traded funds were trading higher. By midday, however, all 11 sectors were in positive territory, with materials, energy, and communication services leading the rotation. This broadening is a positive sign for market health, suggesting that gains are not confined to a handful of megacap names.
Despite the equity strength, bonds offered no relief. The 10-year Treasury yield surged to 5.334%, up 5.7 basis points from Friday's close, as investors digested the latest U.S. services sector data. The ISM Services PMI eased to 54.9 from 55.4, but its prices index climbed to 74.0 from 72.6, reigniting inflation concerns. However, a 1.1% drop in WTI crude oil to $90.08 per barrel helped temper the immediate inflation impulse from commodities, providing some support to equities.
PTC Acquisition Sparks Software Rally
The clearest catalyst for the day's move was the announcement that Schneider Electric agreed to acquire PTC Inc. (NASDAQ: PTC) for $205 per share in cash, valuing the industrial software company at $22.6 billion. The offer represented a 42.3% premium to PTC's Friday close. Shares of PTC surged 33.9% to $192.83, still trading 6.3% below the offer price, reflecting time, financing, and completion risks. Rosenblatt analyst Blair Abernethy said, "We expect this deal to be completed as planned," while several firms, including Loop Capital, Rosenblatt, and Stifel, adjusted their ratings to Hold or Neutral with $205 price targets.
The deal also sparked a reassessment of industrial software valuations, lifting shares of Autodesk (NASDAQ: ADSK) by 3.8%. Meanwhile, Schneider Electric's shares fell 10.0% in Paris as investors weighed the cost of the acquisition.
RXO and C.H. Robinson: A Contrasting Deal
A second transaction created sharper dispersion in the market. RXO Inc. (NYSE: RXO) jumped 21.8% to $28.49 after C.H. Robinson Worldwide (NASDAQ: CHRW) announced a $5.8 billion cash-and-stock acquisition. The consideration was $17.25 in cash plus 0.0856 of a C.H. Robinson share per RXO share, valued at about $29.10 at midday prices. The spread was much narrower than PTC's, but RXO holders were exposed to C.H. Robinson's falling share price, which dropped 12.2% to $138.41. The deal's structure highlighted the complexities of stock-based transactions in a volatile rate environment.
Market Breadth and Sector Performance
Beneath the headline indices, participation remained uneven. Advancers represented 60.8% of all NYSE issues, but Nasdaq decliners outnumbered advancers even as the composite approached record levels. Large software and megacap moves carried unusual weight, suggesting that the rally's sustainability may depend on continued leadership from these names.
Among sectors, materials (XLB) led with a 1.31% gain, followed by energy (XLE) at 1.15% and communication services (XLC) at 1.02%. Utilities (XLU) added 0.88%, financials (XLF) rose 0.69%, and real estate (XLRE) was nearly flat at 0.02%, reflecting sensitivity to rising yields.
Risks and Outlook
Investors are closely watching the 10-year Treasury yield, which is testing the 5.35% level. A break above that could reverse the software bid and pressure rate-sensitive sectors. Additionally, weaker Nasdaq breadth could reopen the gap between index gains and underlying participation.
The next major test comes Wednesday, October 7, at 2 p.m. EDT, when the Federal Reserve releases the minutes from its September meeting. Investors will scrutinize the minutes for clues on whether officials view services inflation as warranting another rate increase. The combination of elevated yields, robust M&A activity, and mixed economic data keeps the market in a delicate balance.