Shares of Manchester United plc (NYSE:MANU) slid 3.5% to $20.205 by 14:05 EDT on Friday, as investors weighed a record revenue forecast against a stagnant profit outlook. The decline followed the club's preliminary fiscal 2026 results, which showed record revenue but a widening net loss.
The company guided fiscal 2027 revenue to a range of £740 million to £760 million, implying a 10.7% increase at the midpoint. However, adjusted EBITDA is projected at £205 million to £225 million, with a midpoint of £215 million—slightly below the £216.4 million reported for fiscal 2026. Management attributed the flat profit outlook to higher player wages and transfer amortization costs.
For fiscal 2026, Manchester United reported total revenue of £677.6 million, up 1.7% from the prior year, driven by a 19.6% surge in broadcasting revenue to £206.8 million. Commercial revenue fell 4.8% to £317.3 million, and matchday revenue declined 4.2% to £153.5 million. Adjusted EBITDA rose 18.4% to £216.4 million, and operating profit turned positive at £22.6 million, but the net loss widened to £43.0 million from £33.0 million.
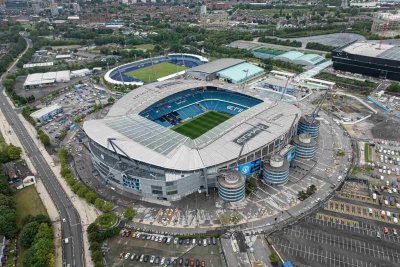
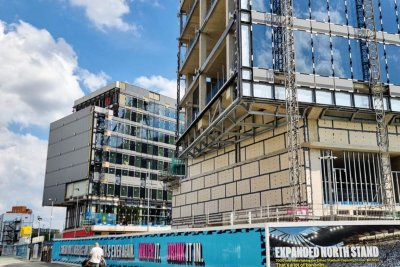
Employee costs decreased 3.6% to £302.0 million after prior headcount reductions, providing some operational leverage. Cash flow from operations improved sharply to £178.7 million from £72.7 million, while property spending doubled to £85.9 million, including £63.5 million for land acquisition related to the planned stadium redevelopment.
The balance sheet remains a key concern. Calculated net borrowings rose 12.9% to £621.7 million as of June 30, and net finance costs more than tripled to £69.6 million. Total borrowings increased 8.2% to £689.0 million, with non-current borrowings up 22.4% to £577.6 million. Cash and equivalents fell 21.9% to £67.2 million.
The fiscal 2027 guidance assumes continued participation in the Champions League, which could boost revenue at the upper end of the range. However, management explicitly included higher player costs in the outlook, which could offset incremental revenue. Investors are also awaiting a final budget and funding structure for the stadium project, which adds another layer of capital expenditure uncertainty.
Analyst coverage remains sparse, with only two firms providing current ratings. The consensus is a Buy, with an average price target of $23.02, implying 13.9% upside from Friday's price. UBS has a Buy rating with a target of $31.00, while Deutsche Bank holds a Hold with an $18.50 target. The stock traded at 1.87 times its average volume by 14:05 EDT, indicating heightened investor attention, though it remains 36.1% above its 52-week low of $14.85.
Risks include UEFA performance shortfalls, player spending absorbing incremental sales, and exposure to exchange rate movements on dollar-denominated debt. The next catalyst is the audited annual report, which will confirm whether the preliminary EBITDA figure survives scrutiny.