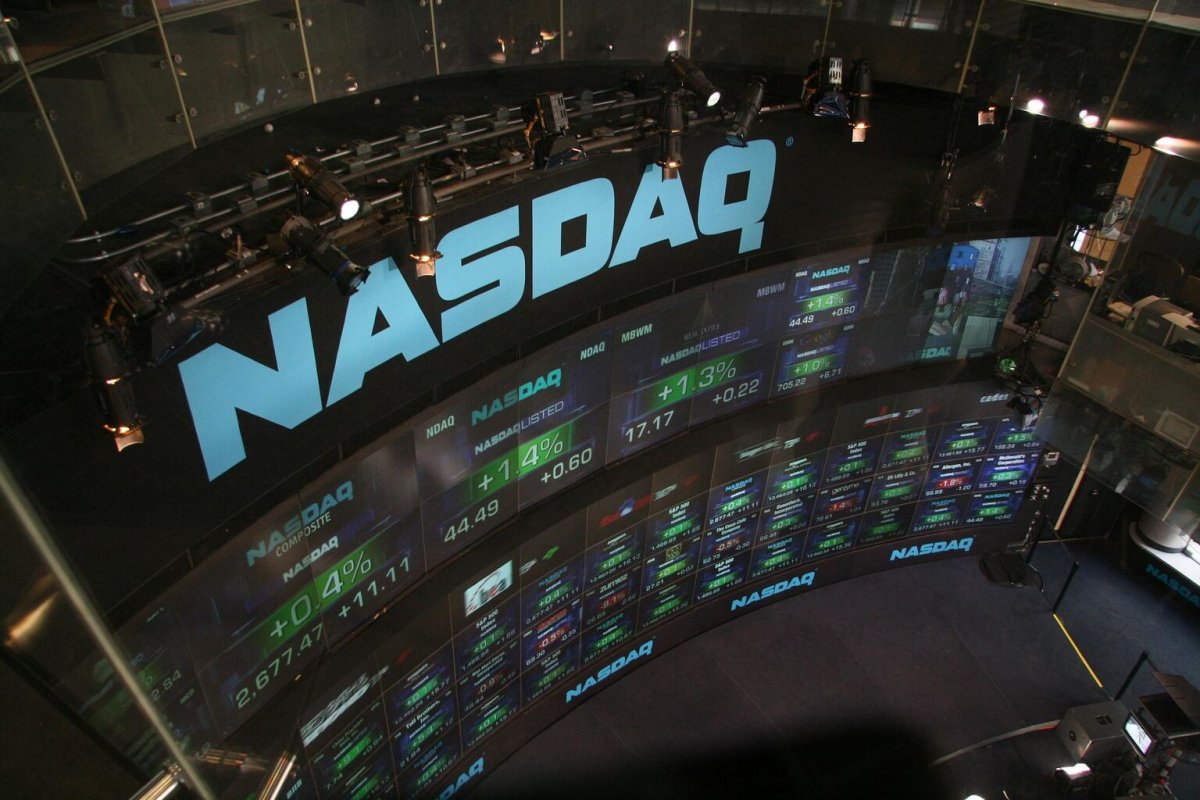
The Nasdaq 100 finished Wednesday's session with a gain of 0.91%, even as semiconductor stocks suffered a sharp sell-off. The tech-heavy benchmark closed at 28,437.17 points, according to delayed data from Nasdaq's quote service. Meanwhile, the equal-weight version of the index, which assigns the same weight to each constituent, rose 1.23% to 9,923.23 points, suggesting that the advance was not solely driven by the largest companies.
In stark contrast, the PHLX Semiconductor Index (SOX) dropped 3.13% to 10,268.65 points. The chip sector's session range was notably wider, with a high-low span equal to 5.54% of Tuesday's close, compared to just 1.96% for the Nasdaq 100. That makes the semiconductor range approximately 2.8 times larger than the benchmark's, underscoring the volatility in chip shares.
The divergent performance highlights the different composition of the indices. The Nasdaq 100 includes the 100 largest non-financial companies listed on the Nasdaq, as tracked by Invesco's QQQ ETF (QQQ). The equal-weight methodology, used by the NDXE index, reduces the influence of mega-cap stocks by resetting each constituent to a 1% weight quarterly. The SOX index, on the other hand, is composed of 30 companies involved in chip design, manufacturing, distribution, and sales, including heavyweights like NVIDIA (NVDA), AMD (AMD), and Intel (INTC).
The market's rebound followed the Democrats' victory in the congressional midterm elections. Reuters reported that investors anticipated a divided government would limit major policy shifts, which is often seen as positive for markets. However, data-center stocks faced pressure due to concerns over potentially stricter regulation of artificial intelligence. Those competing forces helped shape the session's policy debate but do not fully explain individual price movements.
"Markets typically respond positively to midterm elections being over, no matter what the outcome," said Michael Townsend, managing director of legislative and regulatory affairs at Charles Schwab, in the firm's morning note. His comments came before the afternoon readings.
Despite Wednesday's gain, the Nasdaq 100 remains well below its October levels. It is about 9.3% below Schwab's rounded early-October reference of 31,361 points. To return to that level, the index would need to climb roughly 10.3% from its current 28,437.17.
Looking ahead, investors will turn their attention to economic data. The Bureau of Labor Statistics is scheduled to release preliminary third-quarter productivity and costs figures on Thursday, November 5, at 8:30 AM EST. The October employment report will follow on Friday, November 6, also at 8:30 AM EST. These reports will provide further insight into the economy's investment returns and labor costs, which could influence market sentiment.
As of now, the possibility of data-center restrictions remains a regulatory uncertainty rather than an enacted federal investment limit. Any delays in permits or construction could alter spending schedules and semiconductor orders, adding another layer of risk for chipmakers.