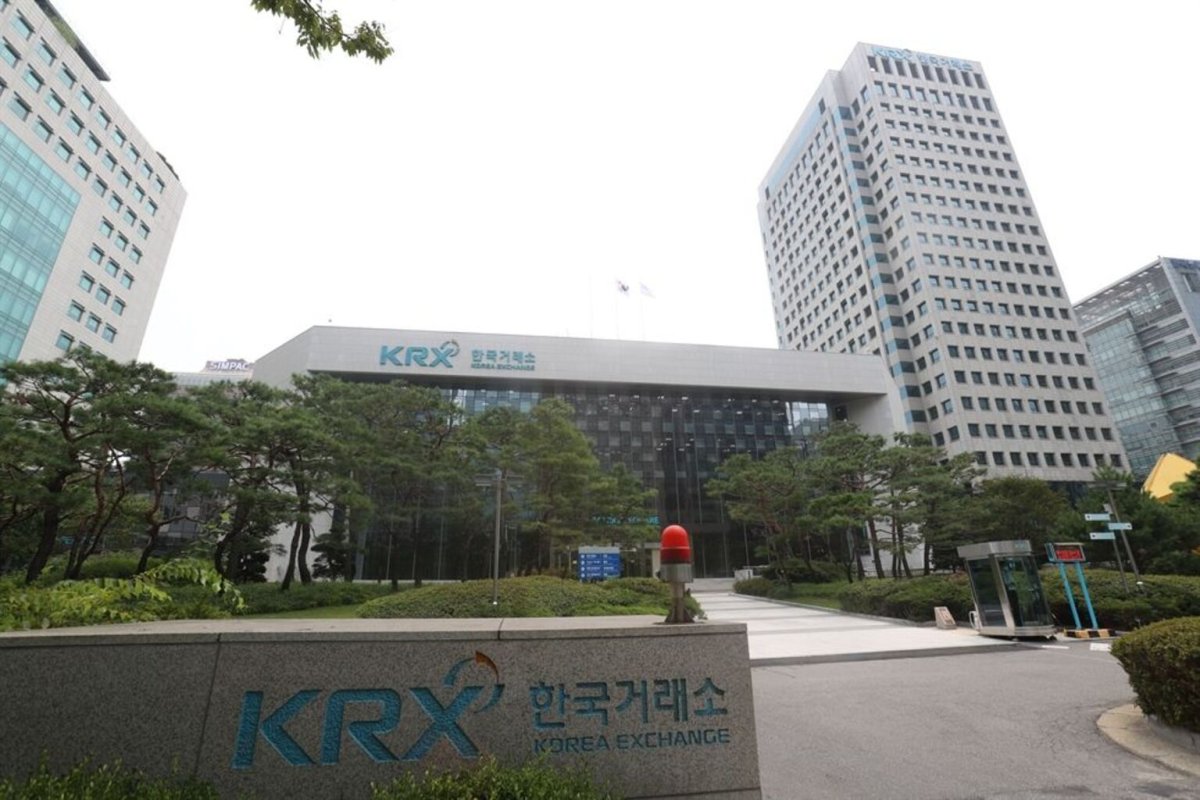
Asian equities advanced on Monday, with South Korea's benchmark KOSPI index breaching the 7,000-point milestone for the first time, as a rally in semiconductor stocks lifted sentiment. The KOSPI climbed 1.79% to reach 7,017.38 in afternoon trading in Seoul, driven by strong gains in heavyweight technology names.
Chip Stocks Lead the Advance
Samsung Electronics (SSNLF) surged nearly 4%, while SK hynix added about 1%, providing the primary momentum for the KOSPI's record-breaking move. However, the rally was notably narrow, with declining stocks outnumbering advancers on the index, according to Aju Press. This concentration in a few large-cap tech names raises concerns about the sustainability of the advance.
Other Asian markets also posted gains. Hong Kong's Hang Seng index rose 0.57% to 24,891.58, and the Shanghai Composite added 0.55% to 3,933.37. Australia's S&P/ASX 200 was nearly flat, down 0.04%, while India's Nifty 50 edged up just 0.06%. Japan's cash equity market was closed for Respect for the Aged Day, leaving regional trading volumes thinner than usual.
Bond Yields Cast a Shadow
The positive tone in Asia comes against a backdrop of persistent pressure from rising bond yields. The U.S. 10-year Treasury yield closed at 4.998% on Friday, up 5.1 basis points, adding to the valuation headwinds facing growth-oriented equities. Higher yields increase the discount rate applied to future earnings, making expensive stocks less attractive.
Friday's handoff from Wall Street was mixed. The S&P 500 and Nasdaq Composite advanced 0.17% and 0.39%, respectively, but the Dow Jones Industrial Average slipped 0.18%. European markets were weaker, with the FTSE 100 down 0.27% and the Euro Stoxx 50 falling 1.37%. This divergence suggests that the chip-driven strength in Asia lacks broad global confirmation.
Oil Prices Provide Some Relief
Crude oil prices offered a cushion for risk sentiment. WTI futures fell 2.12% to $94.04 per barrel, easing immediate inflation concerns. The retreat was attributed to recovering Middle East exports, although geopolitical risks remain elevated. Lower oil prices can help alleviate input cost pressures for businesses and consumers.
Europe's Busy Week
Investors now turn their attention to Europe, where a series of key economic data and central bank decisions are due. On Wednesday, flash PMI readings for the Eurozone and the UK will provide an early snapshot of economic activity in September. The following day, three central banks—the Riksbank, Norges Bank, and the Swiss National Bank—will announce their latest monetary policy decisions.
The Riksbank's decision on Thursday at 09:30 CET will be closely watched for signals on the Swedish rate path. Norges Bank follows at 10:00 CET, with the Norwegian rate and krone in focus. The Swiss National Bank's assessment at 09:30 CET will be scrutinized for any intervention guidance regarding the franc.
Earnings vs. Discount Rate
The fundamental question for equity markets is whether corporate earnings can outpace the rising discount rate. DWS Group (DWS) expects positive returns for major indices through June 2027, but its models incorporate a drag from valuation compression. For U.S. equities, DWS forecasts 12.5% earnings growth but assigns a 3.6% negative impact from multiple contraction. In Europe, slower growth is offset by higher dividend yields, supporting total return potential.
DWS's targets include an S&P 500 level of 8,400 (10.2% total return), a Stoxx Europe 600 target of 690 (9.7%), and a Euro Stoxx 50 target of 6,900 (11.0%). The FTSE 100 is seen reaching 11,300 (7.9%), while MSCI AC Asia ex Japan is projected at 1,180 (6.2%).
However, the narrow breadth of Monday's rally is a cautionary signal. If AI-related spending expectations falter, the concentrated gains in chip stocks could reverse quickly, dragging down the broader market.
Risks Ahead
Key risks include a fresh spike in oil prices or another break above 5% in the 10-year Treasury yield, which could erase the valuation relief seen on Monday. Japan's extended market closure may also overstate regional calm by thinning liquidity. The upcoming PMI data and central bank decisions will test whether earnings optimism can withstand tighter financial conditions.