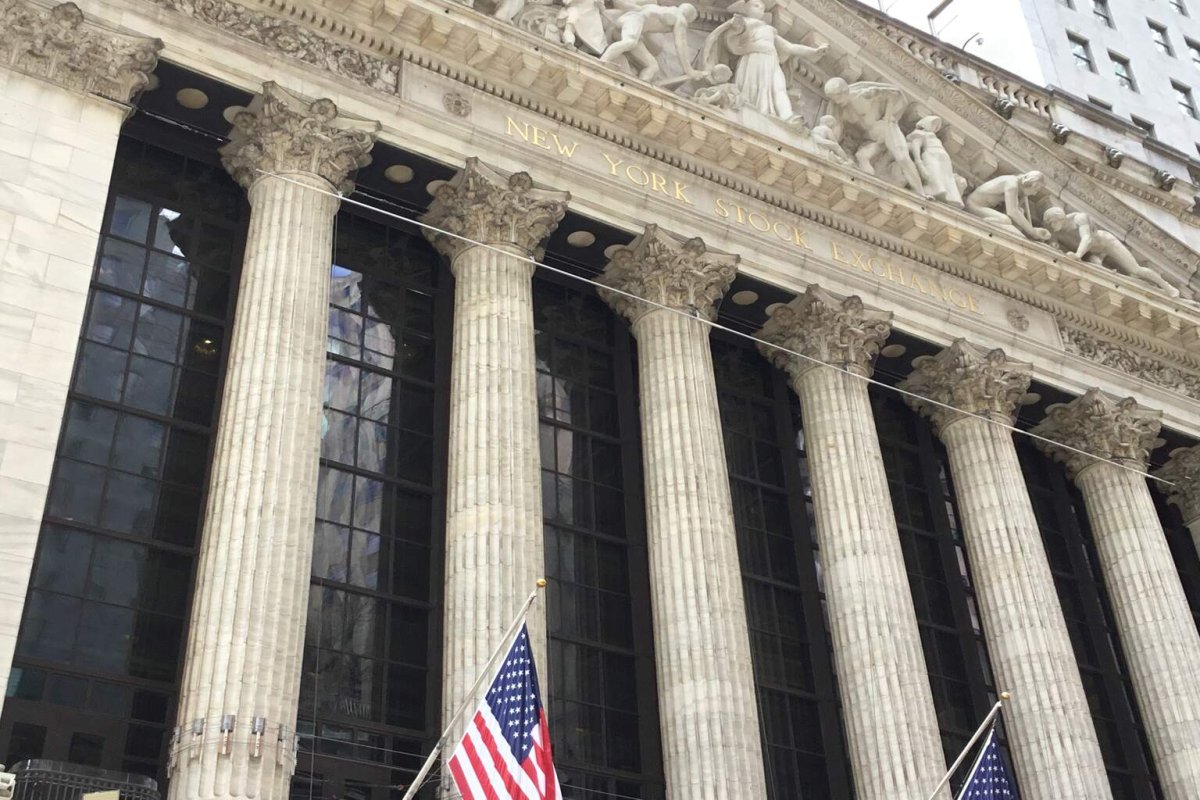
U.S. equities finished higher on Thursday, October 15, 2026, but the gains were not driven by the technology sector. The S&P 500 closed at 7,744.06, up 0.33%, recovering from an early decline of 0.64%. The Dow Jones Industrial Average rose 1.08% to 52,177.69, and the Russell 2000 added 1.38% to close at 2,767.27. The Nasdaq Composite lagged with a gain of just 0.08%, ending at 26,713.02.
The session featured a notable intraday reversal. The Nasdaq climbed 1.26% from its opening level and 1.54% from its low, masking the strength of the recovery beneath its modest closing gain. Market breadth confirmed a rotation away from technology: approximately seven out of ten S&P 500 constituents advanced, and eight of the eleven liquid sector proxies ended in positive territory.
Sector Performance
Health care, materials, and consumer discretionary led the gains. The health care sector ETF (XLV) rose 1.86%, materials (XLB) added 1.79%, and consumer discretionary (XLY) gained 1.71%. Communication services (XLC) and financials (XLF) also outperformed, rising 1.46% and 1.38%, respectively. Technology (XLK) slipped 0.65%, and energy (XLE) dropped 1.58% despite a late rally in oil prices.
Inflation and Rates
Falling Treasury yields helped support equity valuations. The 10-year Treasury yield declined nine basis points to 5.10%, while the 2-year yield fell five basis points to 4.77%. The move came even as the Labor Department reported that September producer prices increased 1.3% month-over-month and 6.3% year-over-year, a fresh inflation shock that investors largely absorbed.
Earnings and Stock Moves
Marsh & McLennan Companies (NYSE: MRSH) gained 4.52% after reporting adjusted earnings of $2.03 per share, a 10% increase. CEO John Doyle highlighted “strong third quarter” results, including 5% underlying revenue growth and double-digit EPS growth. In the AI space, NVIDIA (NASDAQ: NVDA) fell 1.84%, while CoreWeave (NASDAQ: CRWV) staged a dramatic reversal, closing 5.94% higher after dropping 9.5% in the morning. According to PitchBook analyst John Atkins, CoreWeave serves as a “bellwether for the riskier cusp of hyperscaler sentiment.” The company disclosed $5.52 billion in cash as of June 30 and warned that debt could constrain financing; its quarterly filing also showed a $4.0 billion accumulated deficit.
Commodities, Currencies, and Crypto
Outside equities, the U.S. dollar weakened, with the dollar index down 0.46% to 102.08. November WTI crude traded near $98.07, up 3.1%, after the Energy Information Administration reported an 8.6-million-barrel draw in commercial inventories. December gold rose 1.56% to $4,171.80, and Bitcoin gained 0.84% to $82,226.
Analyst Actions
Research calls favored selective broadening. Baird upgraded Zions Bancorporation (NASDAQ: ZION) from Neutral to Outperform with a $75 target. Deutsche Bank raised Walmart (NASDAQ: WMT) from Hold to Buy with a $136 target. Baird downgraded Align Technology (NASDAQ: ALGN) from Outperform to Neutral with a $162 target.
Looking Ahead
Risks remain: a renewed rise in yields or wider AI-related credit spreads could quickly reverse Thursday’s small-cap and cyclical gains. On Friday, September import prices are due at 8:30 a.m. EDT, followed by the Federal Reserve’s industrial production and capacity utilization report at 9:15 a.m. The Fed’s next policy meeting is scheduled for October 27-28. The immediate test will be whether industrial output can validate cyclical leadership without pushing the 10-year yield back above 5.19%.