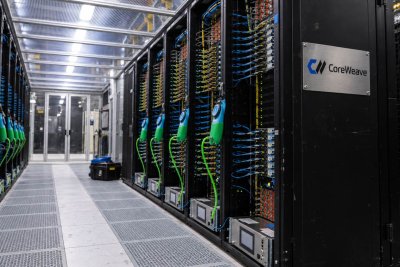
CoreWeave's stock retreated from earlier premarket gains on Thursday after the AI cloud infrastructure provider disclosed a two-pronged capital raise. The company filed an 8-K with the SEC on September 17 outlining a proposed $3.0 billion convertible senior notes offering, a $500 million purchase option, and a separate equity distribution agreement that could see up to 35 million Class A shares sold into the market.
At 9:29 a.m. ET, shares traded at $81.50, down $1.85 or 2.22% from Wednesday's close of $83.35, according to Nasdaq real-time data. Premarket volume reached approximately 9.4 million shares. The reversal is notable because the stock had climbed above $88 earlier in the session before the financing details emerged, reflecting investor anxiety over potential dilution.
Convertible Terms and Dilution Mechanics
The convertible notes mature on April 1, 2033. CoreWeave's offering presentation indicates an expected coupon range of 2.375% to 2.875% and a conversion premium of 22.5% to 27.5%. Final pricing is expected after the market closes on September 17, so these figures remain subject to change.
These terms are significantly more favorable than much of CoreWeave's existing debt. The company's June-quarter filing listed senior notes with coupons ranging from 8.5% to 9.75%, while two earlier convertible issues carried 1.75% coupons. At the midpoint of the new range, the $3.0 billion raise would generate roughly $79 million in annual cash interest before fees—an illustrative calculation rather than company guidance.
The dilution picture involves three moving parts. CoreWeave may settle conversions in cash, shares, or a combination. It also plans capped-call transactions designed to limit dilution below a yet-to-be-disclosed cap. Separately, the equity-distribution agreement allows the sale of up to 35 million shares through at-the-market transactions, block sales, or collared forwards. The company has agreed not to use this program for at least 30 days following the convertible purchase agreement.
That 35 million shares represents about 7.7% of the 457 million Class A shares outstanding as of June 30, or 6.4% of the combined 551 million Class A and Class B shares. At $81.50, the full allotment would have a notional value of roughly $2.85 billion before commissions of up to 2%. CoreWeave has not committed to selling every share, and actual proceeds will depend on market timing and price.
Why CoreWeave Keeps Returning to Capital Markets
This is not financing for a mature software company with light capital needs. CoreWeave spent $14.1 billion on property and equipment in the first half of 2026. Its June 10-Q shows $3.66 billion in operating cash inflow, $14.87 billion in investing cash outflow, and $13.99 billion in financing cash inflow over the same period.
The balance sheet already carried $35.55 billion in debt principal at June 30, including $31.41 billion of net recourse debt and $3.66 billion of net non-recourse debt. Contractual interest expense totaled $1.08 billion for the first six months. CoreWeave had $5.52 billion in cash and $10.01 billion in undrawn secured capacity at quarter-end, then added a $2.6 billion delayed-draw facility in August and drew $1.2 billion from it.
The strongest argument for accepting this financing burden is contracted demand. CoreWeave reported $2.58 billion in second-quarter revenue, $104.2 billion in revenue backlog, and more than $25 billion in net new commitments added early in the third quarter. Committed contracts supplied 98% of second-quarter revenue. The offering document notes that contracts signed in the second quarter carry an expected contribution margin about 25% higher than recent quarters, and some deals include customer prepayments.
The counterargument sits in the same numbers. Backlog becomes revenue only after CoreWeave delivers capacity and maintains availability. The company must often purchase GPUs, networking equipment, and data-center capacity before collections catch up, which is why debt and equity issuance remain part of the operating model rather than an occasional event.
What to Watch Next
Investors can assess three key items in the coming days. First, the final coupon and conversion premium after Thursday's close. Second, the capped-call ceiling, which defines where dilution protection ends. Third, whether CoreWeave actually uses the 35-million-share program once its 30-day standstill expires.
A low coupon and high conversion threshold would make the convertible a relatively efficient way to fund contracted growth. Heavy ATM use, weaker contract margins, or another jump in capital spending would reinforce the market's more skeptical view: customer demand is strong, but shareholders are still being asked to finance the gap between signed contracts and delivered computing capacity.