Fluence Energy (NASDAQ: FLNC) has once again reduced its financial guidance for fiscal 2026, this time by a much larger margin than the previous adjustment. The battery-storage provider now expects revenue of approximately $2.4 billion for the fiscal year, down from the $2.9 billion to $3.1 billion range it had provided just six weeks earlier. Additionally, the company projects an adjusted EBITDA loss of roughly $200 million, a significant deterioration from its prior forecast of a $30 million loss to a $10 million profit.
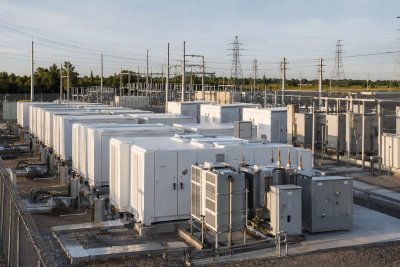
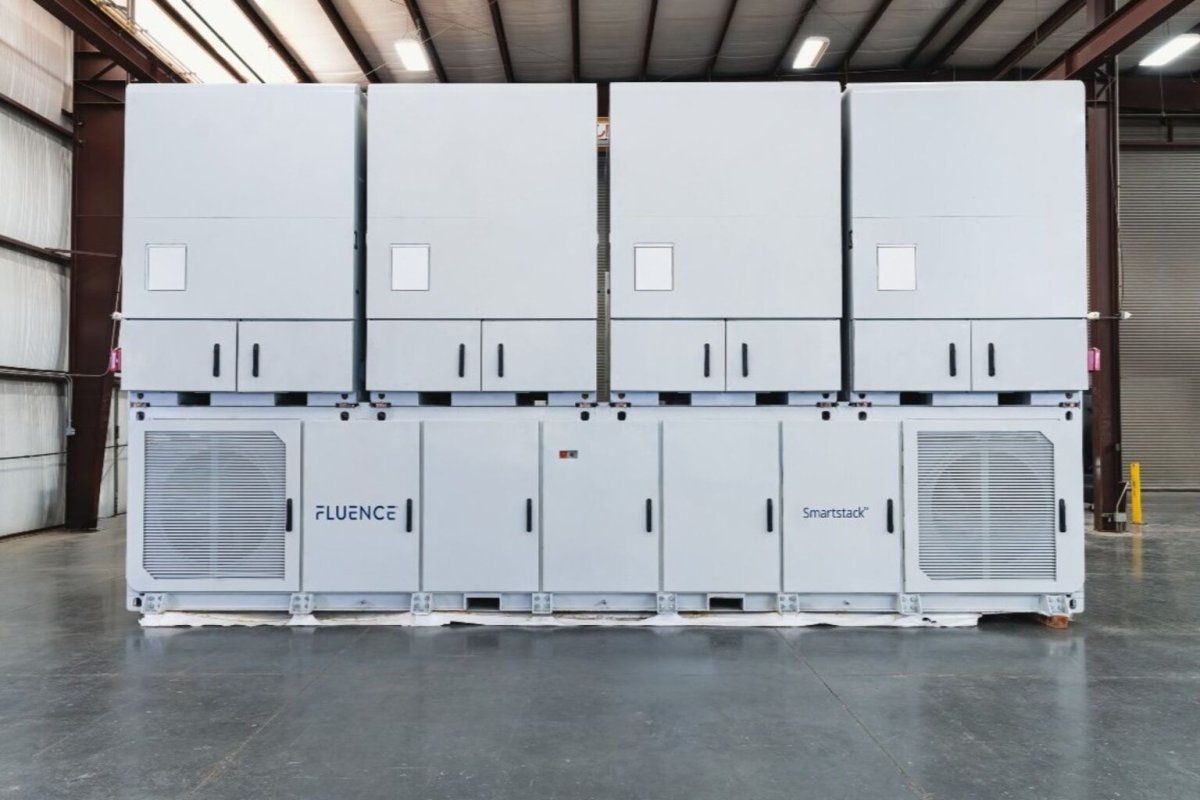
The revised outlook comes as Fluence continues to grapple with production ramp-up issues at a contract-manufacturing facility in Houston. The company had previously disclosed in August that $400 million of project deliveries would be delayed into fiscal 2027 due to manufacturing and construction challenges. However, the latest announcement indicates that the problems are more severe than initially anticipated, with an additional $600 million in revenue being pushed out of the current fiscal year.
Shares of Fluence tumbled 19.8% in after-hours trading, falling to $7.26 from Wednesday's close of $9.05, according to Yahoo Finance data. The market reaction underscores investor concerns about the company's ability to execute on its backlog and convert its record order book into actual revenue.
CEO Julian Nebreda acknowledged the ongoing difficulties, stating that the contractor has taken corrective action and that daily production has increased. However, the company did not provide specific output figures or a timeline for when it expects to recover the lost schedule. This lack of clarity has left analysts and investors questioning the reliability of Fluence's guidance.
The two consecutive guidance cuts reveal a widening execution gap. When Fluence reported its fiscal third-quarter results on August 5, it had already trimmed its revenue outlook from $3.2 billion to $3.6 billion down to $2.9 billion to $3.1 billion. The latest revision to $2.4 billion represents a 29% reduction from the original midpoint and a $1.0 billion drop. The adjusted EBITDA outlook has worsened by $250 million from the initial range.
The $600 million revenue reduction between the August and September guidance updates resulted in a $190 million deterioration in adjusted EBITDA, a ratio that suggests more than just delayed sales. Start-up inefficiencies, fixed costs, and operational disruptions are weighing on profitability while projects await shipment. This indicates that the company is incurring costs without corresponding revenue recognition, a concerning trend for a business in a growth phase.
Despite the operational setbacks, Fluence's demand pipeline remains robust. As of June 30, the company reported a record backlog of $6.4 billion, which is approximately 2.7 times its new full-year revenue guidance. The backlog includes $850 million in data-center business secured through July. However, backlog is not the same as cash. The company's third-quarter filing notes that customers can terminate contracts or defer services and payments under certain circumstances.
Fluence used $366.5 million in operating cash during the first nine months of fiscal 2026, and as of June 30, it held $365 million in total cash and $863 million in total liquidity, including capacity under working-capital facilities. The projected $200 million adjusted EBITDA loss for the full year raises questions about the company's ability to fund its operations without additional external capital. CFO Ahmed Pasha reiterated the company's fiscal 2027 goal of achieving neutral to positive operating cash flow, but the September update did not provide any new guidance for that year.
Management plans to release a full fiscal 2027 outlook with its year-end results. Until then, investors will be closely monitoring Fluence's ability to ramp up production at its Houston facility and deliver on its backlog. The next financial update needs to provide concrete numbers on daily output, clarify how much of the delayed work is firmly scheduled for 2027, and reconcile the projected loss with available cash resources. Until those details emerge, the record backlog may be more a measure of customer interest than of Fluence's capacity to turn orders into revenue.