Oracle Corporation (NYSE: ORCL) is heading into a pivotal trading session on Monday as news surfaces that $18 billion in loans tied to its Project Jupiter data-center campus have slipped into stressed territory. According to a report from the Financial Times, banks have quoted the debt at just 89 to 91 cents on the dollar, a significant discount that underscores growing unease about the company's aggressive capital spending program.
Market Reaction and Stock Performance
Shares of Oracle closed Friday at $147.61, down 1.98% from the prior session, after touching an intraday low of $144.40. The loan report emerged after the market close, meaning Friday's decline cannot be attributed to this development. However, with volume surging 41.4% to 39.2 million shares, investors are bracing for a potential further drop when trading resumes.
The timing is critical. Oracle's capital expenditure for the quarter ended August 31 reached $28.5 billion, outpacing operating cash flow by roughly $5.4 billion. This funding gap has been partially bridged by customer prepayments of $11.4 billion and a $19.9 billion at-the-market equity offering, but the strain on the balance sheet is evident.
Project Jupiter and Syndication Challenges
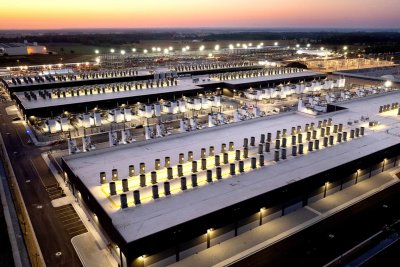
Project Jupiter encompasses a 1,400-acre site in Doña Ana County, New Mexico, and is linked to Oracle's partnership with OpenAI. The syndicate of banks, including Banco Santander (BME: SAN) and Jefferies Financial Group (NYSE: JEF), has reportedly struggled to distribute the loans to other investors. While this debt is separate from Oracle's corporate borrowings, it could raise the cost of future project financing, adding another layer of pressure.
Financial Metrics and Balance Sheet Expansion
Oracle's first-quarter results showed robust growth: revenue climbed 29.6% year-over-year to $19.345 billion, and cloud revenue surged 61.5% to $11.607 billion. Operating cash flow more than doubled to $23.103 billion, but capital expenditure tripled to $28.5 billion, creating a negative free cash flow of $5.4 billion. The balance sheet expanded significantly, with property, plant, and equipment rising by $27.9 billion to $127.8 billion, while total lease commitments reached $288 billion, primarily for data centers.
Analyst Perspectives and Risks
Analyst recommendations are mixed. RBC Capital has a Sector Perform rating with a $165 target, near the current price, while Barclays maintains an Overweight with a $252 target, implying substantial upside if Oracle converts its $664 billion backlog. Other firms like Stifel and Freedom Broker have trimmed targets, reflecting caution about execution risks.
The key risk is that project delays, power constraints, or wider loan discounts could increase financing costs before AI contracts generate sufficient cash flow. Conversely, faster capacity delivery could alleviate these concerns. Monday's session will provide the first measurable signal: whether Oracle can hold Friday's low of $144.40. Investors must weigh the implications of discounted project debt against the company's massive backlog and growth trajectory.