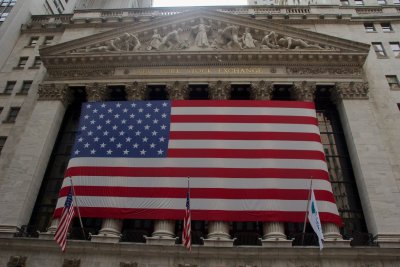
U.S. equities ended Tuesday's session marginally lower, but the headline index masked a more nuanced picture: most S&P 500 constituents were actually advancing shortly before the closing bell. The S&P 500 slipped 1.79 points, or 0.02%, to settle at 7,805.45. The Dow Jones Industrial Average fell 180.45 points, or 0.35%, to 51,670.10.
That divergence is significant. At 3:57 p.m. Eastern, 271 S&P 500 securities were higher while 230 were lower, representing a 53.9% advancing share. Weakness in several large healthcare, banking, and semiconductor names outweighed the positive count. Lower borrowing costs offered only limited support. The 10-year Treasury par yield closed at 5.21%, down three basis points from Friday, while oil retreated, easing one immediate inflation pressure ahead of Wednesday's consumer-price report.
The day was more volatile than the closing numbers suggest. The Dow opened 242 points above Monday's finish, then ended 423 points below its opening print. The S&P 500 and Nasdaq recovered from lower opens but could not hold gains. The Nasdaq Composite lost 0.15% to 27,204.38, and the Russell 2000 shed 0.40% to 2,783.37.
Breadth and Sector Rotation
Sector performance revealed a clear rotation. Energy led with an average constituent gain of 1.83%, even as crude prices fell. Materials added 0.69%, and utilities rose 0.61%. Technology slipped just 0.14%, while financials and healthcare lagged, declining 0.37% and 0.41%, respectively.
Several large losses drove that gap. Applied Materials (NASDAQ:AMAT) dropped 6.9%, Johnson & Johnson (NYSE:JNJ) fell 5.7%, and Citigroup (NYSE:C) lost 5.5%. Micron Technology (NASDAQ:MU) declined 5.1% and was the S&P's heaviest drag, according to the Associated Press.
Mixed Earnings Response
The earnings response was selective. Goldman Sachs (NYSE:GS) reported $17.01 of quarterly earnings per share and an 18.7% annualized return on common equity. Chief Executive David Solomon described the backdrop as a "complicated operating environment" in the bank's results statement.
JPMorgan Chase (NYSE:JPM) earned $5.57 a share, below the $5.93 analyst estimate cited by AP. Wells Fargo (NYSE:WFC) beat the profit estimate but missed revenue expectations. Those mixed results limited support for the financial sector.
Johnson & Johnson's decline was especially notable because the company raised full-year guidance. It reported $25.4 billion in third-quarter sales and adjusted earnings of $2.59 a share. The company's release put adjusted earnings 7.5% below the year-earlier quarter.
Rates and Macro Tape
Treasury yields eased across the curve. The two-year yield slipped one basis point to 4.79%, the 10-year fell three basis points to 5.21%, and the 30-year declined four basis points to 5.56%. The dollar-index futures dropped 0.32% to 102.05. Brent crude slid 0.8% to $105.80 a barrel. The VIX added 0.39% to 15.27.
The Treasury curve still signals a demanding discount rate. The long end remains below Friday's close but near multiyear highs. Current analyst recommendations show how far longer-term views can diverge from one session. Rosenblatt kept its buy rating on Micron with a $1,900 target on Tuesday despite the two-day selloff. TD Cowen initiated Goldman Sachs with a buy rating and $1,050 target on Oct. 8, while Morgan Stanley upgraded Wells Fargo to overweight with a $102 target on Oct. 5.
Risks remain. The breadth count was captured three minutes before the bell, and Wednesday's CPI could quickly reverse Tuesday's yield relief and sector rotation. Fresh company guidance may also reset bank and healthcare valuations. The Bureau of Labor Statistics releases September CPI at 8:30 a.m. EDT on Wednesday, October 14. The next test is whether the 10-year yield stays below Friday's 5.24% after that number lands.